
 |
CENTROlink is a payment infrastructure managed by Lietuvos bankas and intended for payment service providers holding an EEA licence. It enables access to the main SEPA payment schemes through a single integration and the provision of payment services based on a reliable central bank infrastructure. CENTROlink was created for institutions seeking to launch operations faster, grow more efficiently and maintain greater control in the payment process. Over the past decade, the system has grown steadily, and its evolution demonstrates not only technological capability but also market confidence. Clear pricing, additional services and a flexible operating model enable institutions to create secure, competitive and easily scalable payment solutions. |
What you get with CENTROlink
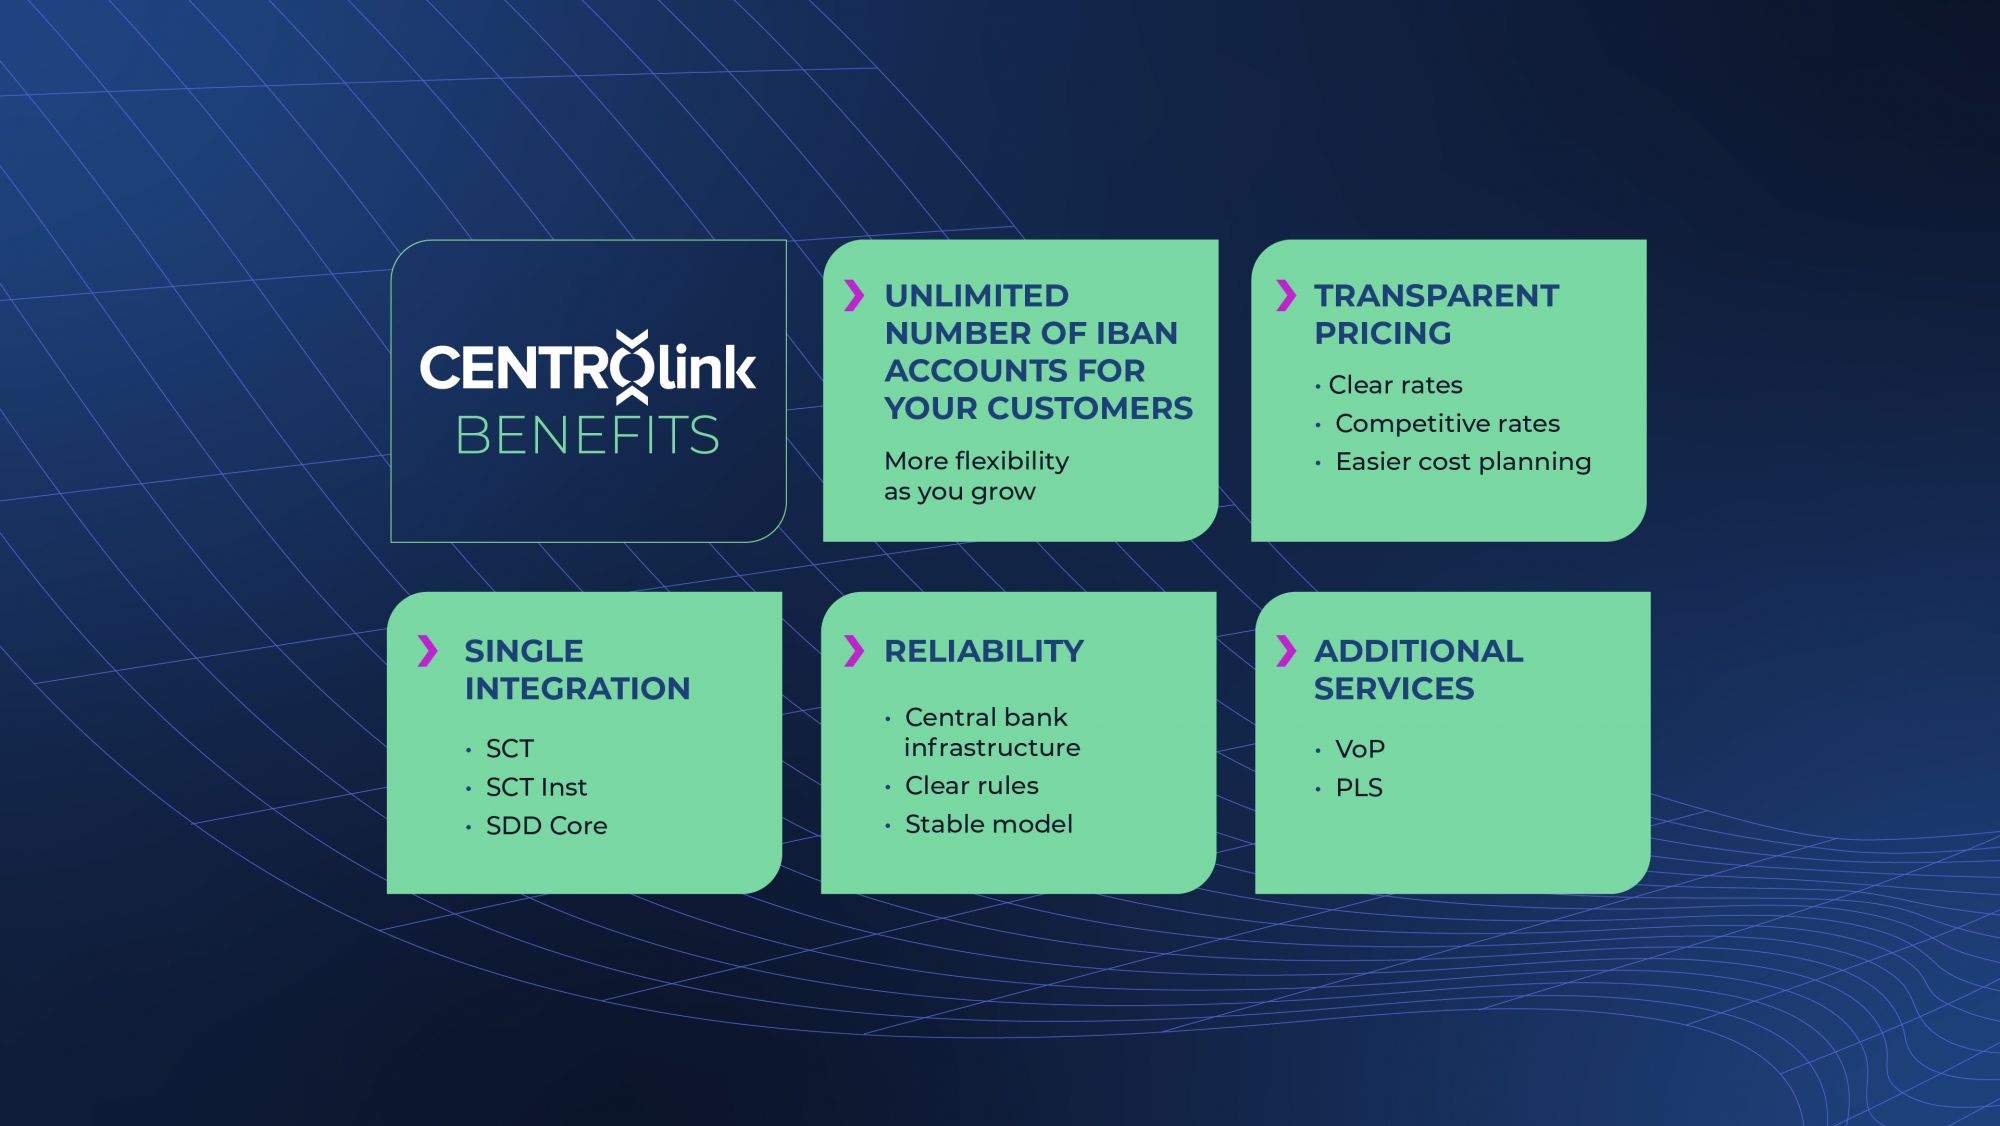
 Direct access to SEPA payments With a single integration, you’ll have access to the SCT, SCT Inst and SDD Core payment schemes. |
Reliability of the central bank infrastructure
Operate within an infrastructure built for stability, security and long-term use. |
| Unlimited number of IBAN accounts
You can open as many IBAN accounts for your customers as you need. |
Transparent and publicly disclosed pricing
Take advantage of a non-profit model with clear and upfront pricing. |
| Additional services within a single infrastructure
CENTROlink participants have access to services such as Verification of Payee (VoP) and the Proxy Lookup Service (PLS). |
More control as you grow
CENTROlink helps you expand your operations while maintaining greater control and reducing dependence on commercial service providers. |

[[#ex]]
What is CENTROlink?
CENTROlink is a payment system operated by Lietuvos bankas that provides access to the single euro payments area (SEPA) for payment service providers (PSPs) licensed within the European Economic Area (EEA), including banks, specialised banks, credit unions, electronic money institutions (EMIs) and payment institutions (PIs).
Who is CENTROlink suitable for?
|
Institutions switching their service provider |
Newly licensed institutions |
|---|---|
|
If you currently process SEPA payments through another service provider, CENTROlink allows you to switch to the infrastructure managed by Lietuvos bankas and gain greater control as you grow. Key benefits:
Three schemes in one place: SCT, SCT Inst and SDD Core.
We help plan the use of BIC during the onboarding process to ensure a smooth transition.
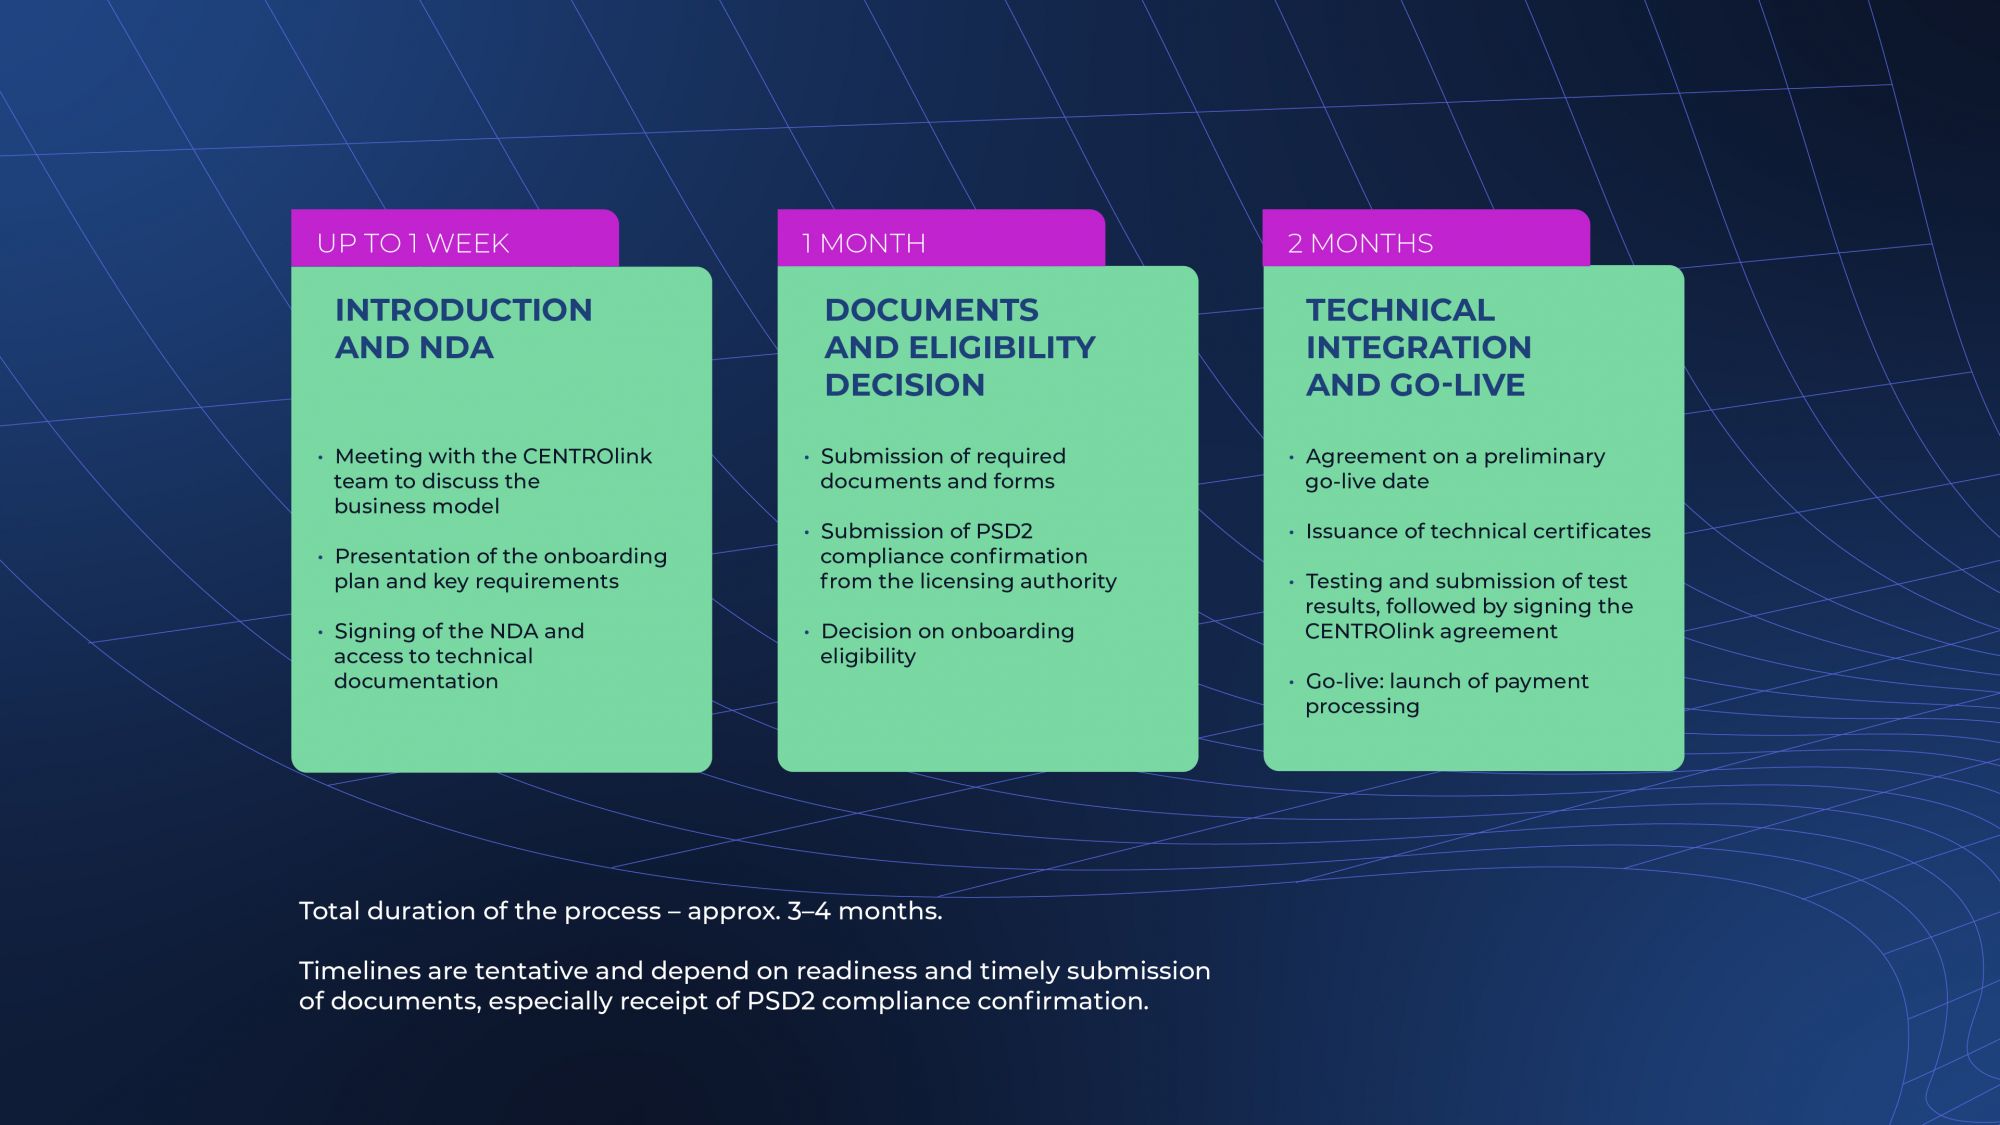
Four stages: introduction and NDA (up to 1 week), documentation and decision (approx. 1 month), integration and testing (approx. 2 months), agreement and start of payment processing.
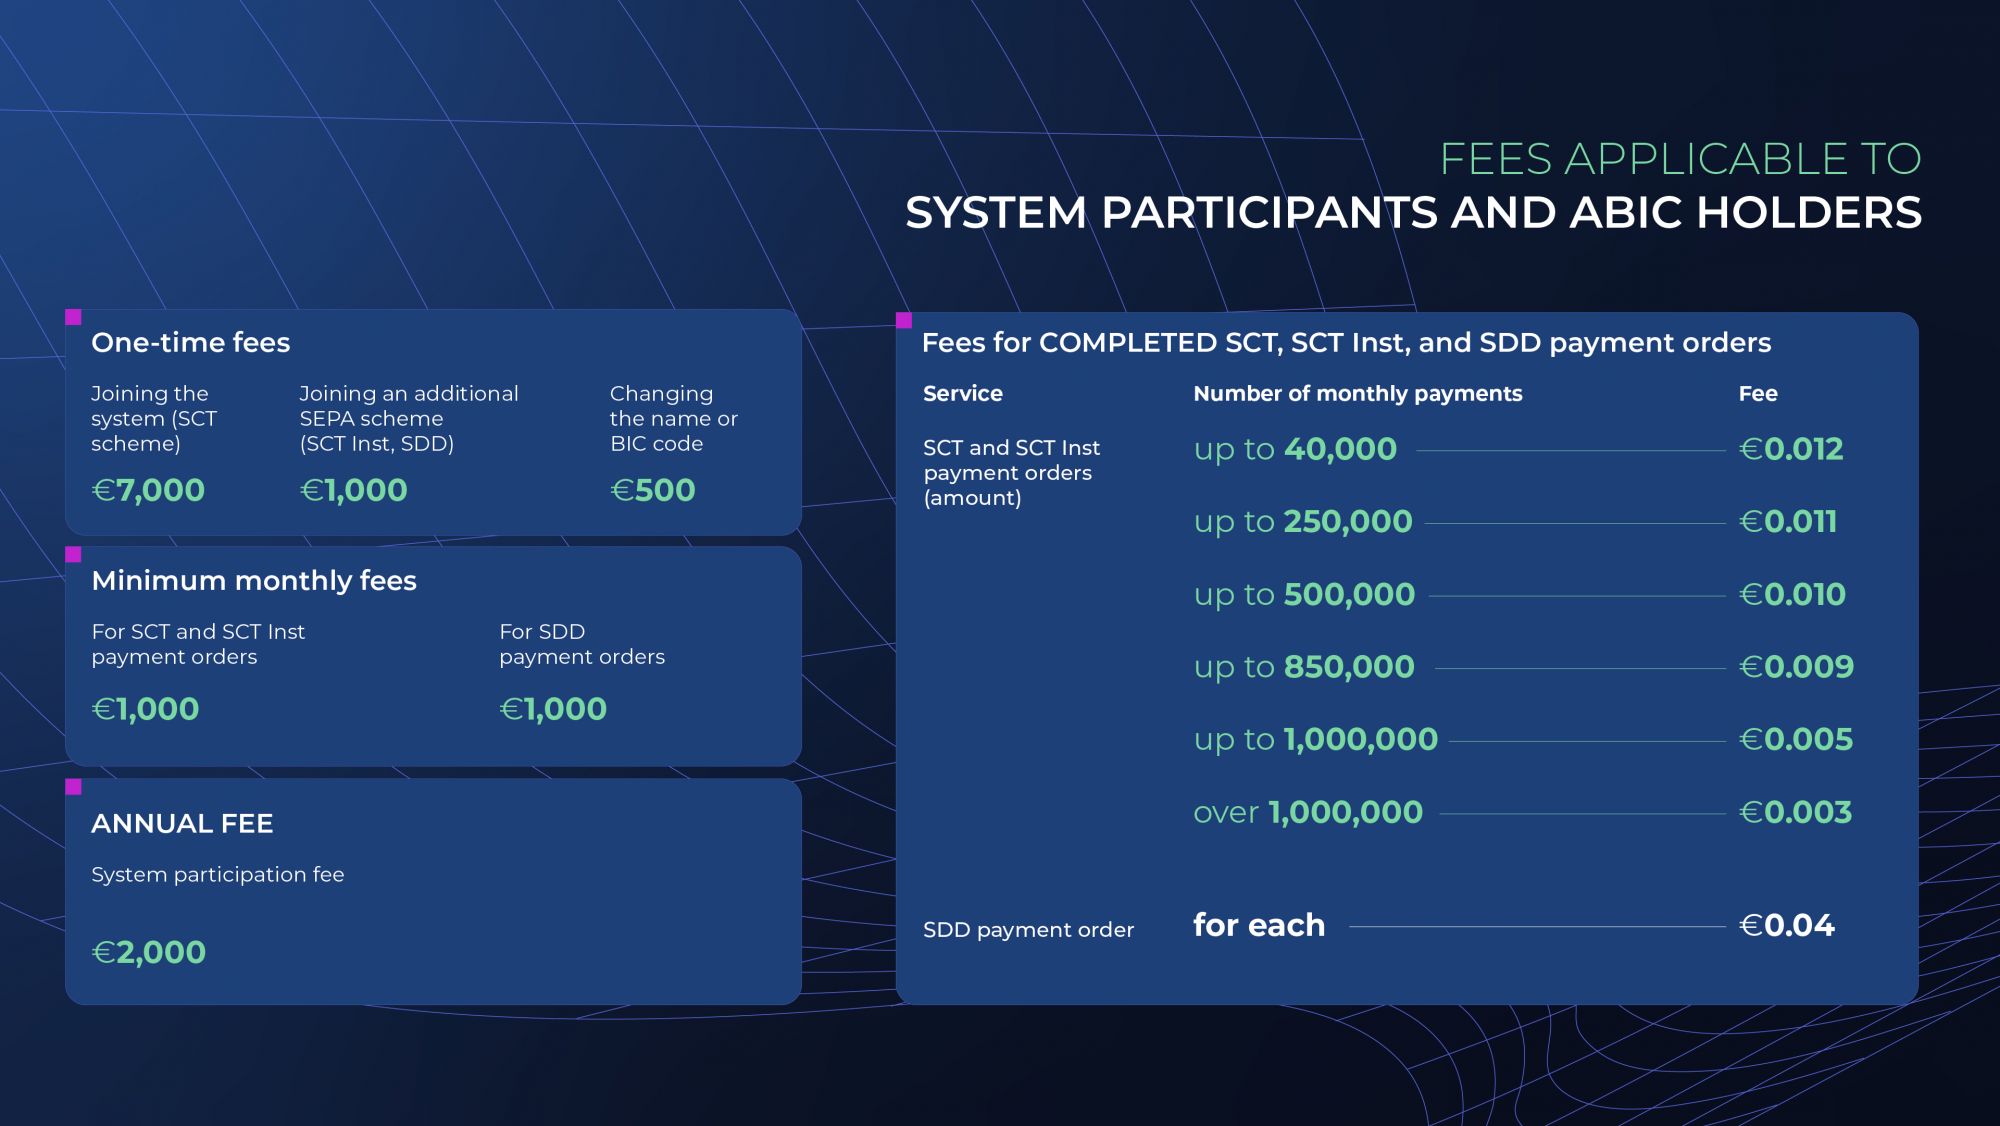
Depending on volume, SCT and SCT Inst fees per payment order can drop to as low as €0.003.
You can open as many IBAN accounts for your customers as needed, with no restrictions.
CENTROlink operates within a payment infrastructure managed by the central bank, and verification of payee (VoP) is available to all CENTROlink participants. |
If you are a new licensed payment service provider, CENTROlink helps you launch SEPA services quickly and establish a path to sustainable growth from day one. Key benefits:
Onboarding and NDA (up to 1 week), documentation and decision (approx. 1 month), integration and testing (approx. 2 months), agreement and start of payments.
SCT, SCT Inst and SDD Core from the very start.
Depending on volume, SCT and SCT Inst fees per payment order can drop to as low as €0.003.
Convenient when the number of customers, product offerings or business volume in different markets is growing rapidly.
CENTROlink operates within a payment infrastructure managed by the central bank, and verification of payee (VoP) is available to all CENTROlink participants. |
Onboarding
Onboarding to CENTROlink is a clear process from the first meeting to the start of payments.
The process is designed to ensure that onboarding is smooth, predictable and tailored to your readiness.
Additional services
In addition to the core SEPA payment schemes, CENTROlink offers its participants additional services that help enhance payment security, convenience and compliance with market and regulatory requirements.
Verification of Payee (VoP)
- What is it?
VoP allows you to check, before making a payment, whether the specified name of the payee matches the account number.
- Practical benefits
This service helps reduce the risk of errors and fraud, improves the customer experience and helps ensure compliance with regulatory requirements. VoP is offered to CENTROlink participants as a convenient integrated solution – with the same integration, there is no need to search for a separate provider, while the service can be obtained in an easily and cost-effective way.
- Who is it for?
Payment service providers who want to ensure safer payments and comply with VoP-related regulatory requirements.
Proxy Lookup Service (PLS)
- What is it?
PLS allows you to initiate a payment using an alternative identifier, such as a mobile phone number or email address linked to the payee’s account, rather than the payee’s IBAN.
- Practical benefits
Payments can be initiated more easily – the payer does not need to know the payee’s IBAN. This is particularly relevant for payments between individuals.
- Who is it for?
Payment service providers who want to offer their customers a more convenient way to initiate payments.
Fees and documentation
Detailed information on all CENTROlink system service fees and the payment procedure for the supply of services is available in the CENTROlink Operating Rules (590.1 KB download icon) and the Rules for Concluding an Agreement with a CENTROlink Addressable BIC Holder.
The fee for system services is calculated separately for each system participant or ABIC holder’s BIC code
FAQ
- Who can become a direct CENTROlink participant?
Payment service providers holding an EEA licence, including banks, specialised banks, credit unions, electronic money institutions and payment institutions, can become direct CENTROlink participants.
- Can electronic money and payment institutions participate in CENTROlink directly?
Yes. Electronic money and payment institutions can become direct CENTROlink participants if they meet the applicable requirements.
- What determines eligibility for becoming a direct participant?
This depends on the country where the institution is licensed and the legal regulations applicable there. Requirements and necessary documents may vary depending on the procedure established by the national supervisory authority.
- What is a document of compliance with Article 35a PSD2?
It is a confirmation from the licensing supervisory authority or other official proof of compliance that the electronic money institution or payment institution meets the requirements of Article 35a PSD2 in order to participate in the payment system.
- Where should I apply for a document of compliance with Article 35a PSD2?
To obtain a document of compliance with Article 35a PSD2, you must refer to the national supervisory authority that issued the operating licence. The authority will inform of which documents are required and the format in which the confirmation is issued.
- Are institutions licensed in Lithuania subject to any additional requirements?
Yes. Electronic money and payment institutions licensed in Lithuania must conduct a self-assessment and submit a compliance report. If required, an audit report or opinion may also be needed.
- How do electronic money and payment institutions currently participate in the CENTROlink system?
Some electronic money and payment institutions participate in the CENTROlink system on the basis of the addressable BIC model. A transition to the direct participation model is currently underway.
- What does the transition to the direct participation model mean?
The transition means that participants meeting the established requirements can switch from the addressable BIC model to direct participation in the CENTROlink system. This requires the assessment of compliance, preparation for legal and operational changes and the delivery of the necessary documents.
- What steps may be required from institutions seeking direct participation?
Depending on the situation, the following may be required:
- ensuring an appropriate method of safeguarding customer funds;
- managing fund balances in accordance with applicable requirements;
- getting ready for the assessment of compliance;
- submitting the necessary documents to the CENTROlink operator.
- Can customer funds be held in central bank-operated payment systems for safeguarding purposes?
No. The safeguarding of customer funds must be ensured as provided for by law; accordingly, institutions must select and implement an appropriate alternative safeguarding method.
- Are the requirements for direct participation the same in all countries?
No. Requirements and documents may vary depending on the country where the licence was issued; you should therefore always be guided by the information provided by your national supervisory authority.
- In which languages can documents be submitted?
Documents may be submitted in Lithuanian or English. If documents are prepared in another language, a translation into Lithuanian or English must be provided.
- Where should compliance documents be submitted?
For specific submission procedures and required documents, it is recommended to contact the CENTROlink team directly.
Official list of systems and their participants
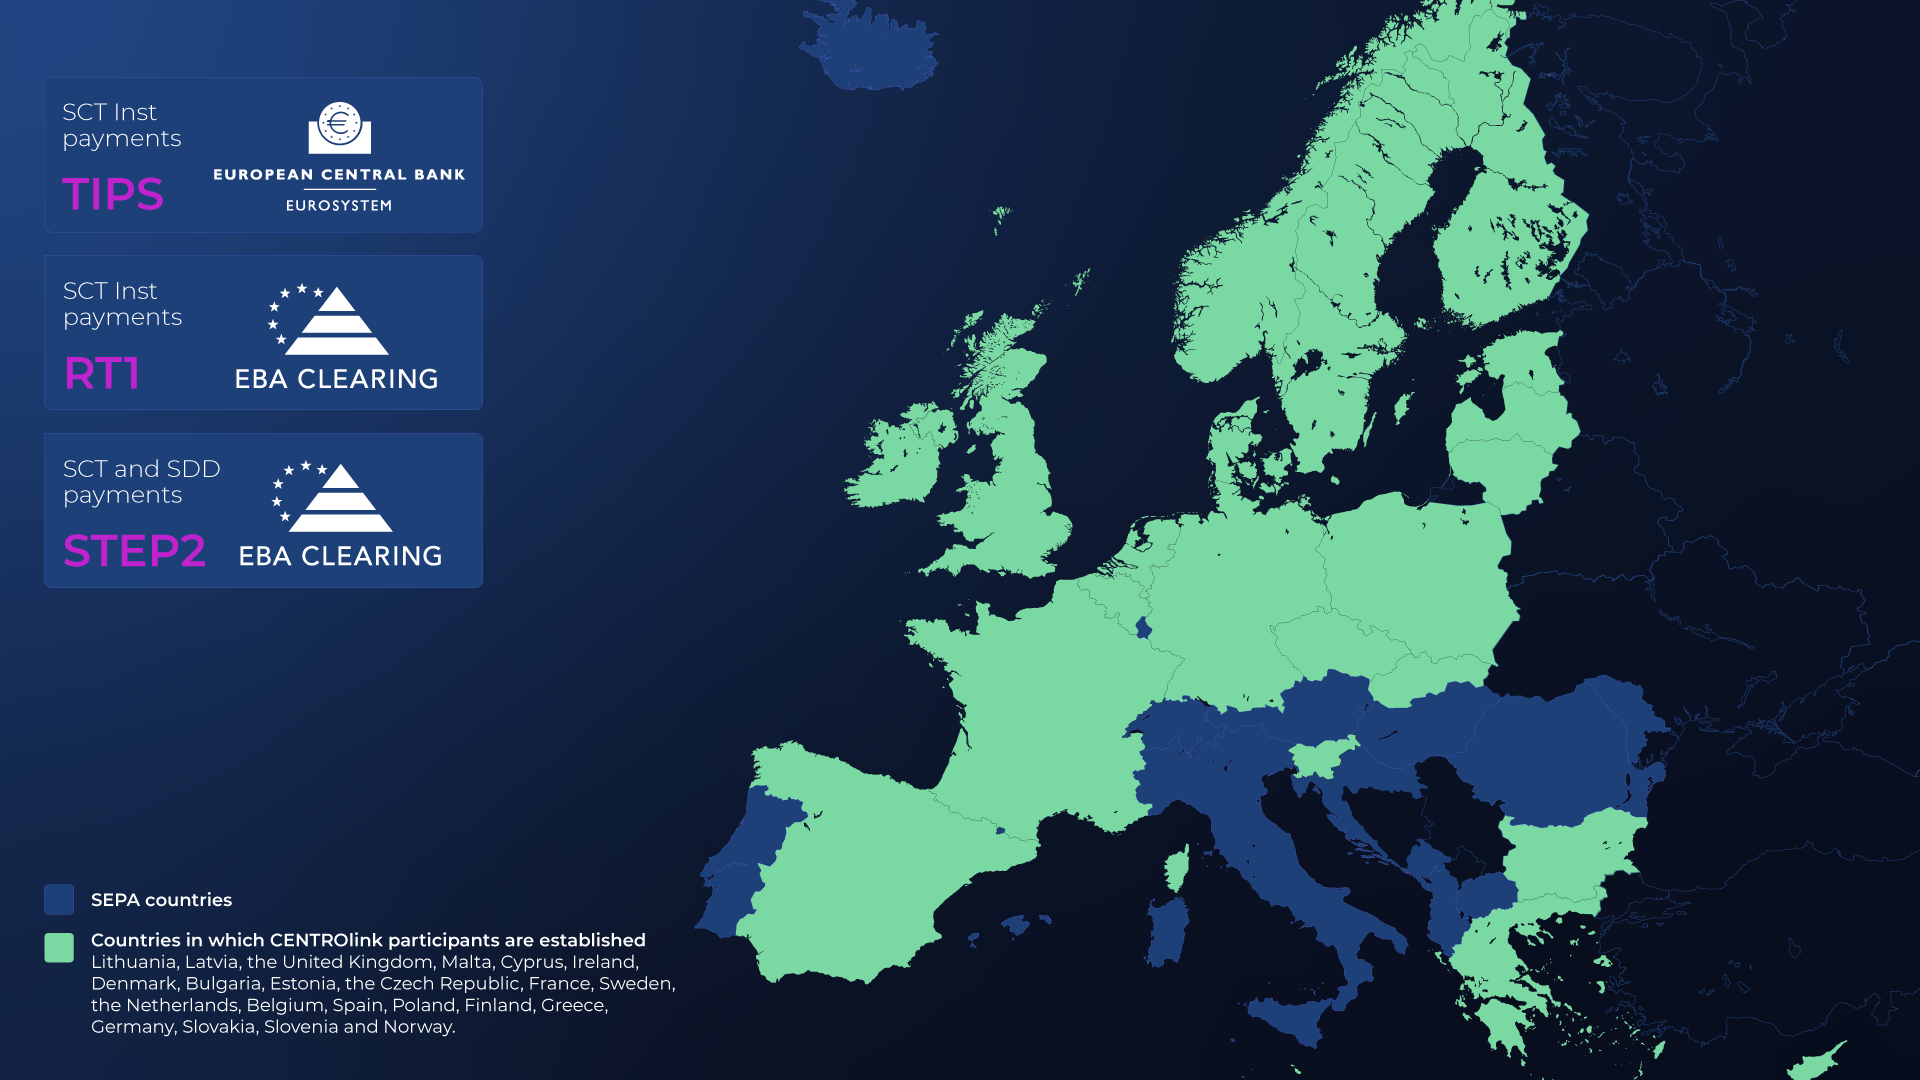
Launched a decade ago as a new payment system, CENTROlink has grown into a reliable European retail payment infrastructure. It currently enables financial institutions across Europe to process SEPA payments in euros and connects both traditional banks and innovative FinTech market participants through a single platform.
The CENTROlink community has grown with the system to include more than 200 financial institutions from over 20 countries, and today CENTROlink is actively used by more than 140 participants, such as direct participants, addressable BIC holders operating through them and participants’ branches. For many partners, CENTROlink has become a reliable foundation for joining the SEPA ecosystem, effectively expanding services and developing new solutions.
The official list of systems and their participants includes the direct participants of the CENTROlink payment system.
Official list of systems and their participants
[[#ex]]