
2026-06-29

Balance Sheet and Interest Rates of Monetary Financial Institutions, May 2026
Today, Lietuvos bankas published the balance sheet and interest data of the monetary financial institutions (MFI) for May 2026, which show that:
- Lithuanian resident (household) deposits decreased by €338.3 million, or 1.1%, over the month, while interest rates on new deposits went up by 0.14 p. p.;
- corporate (non-financial corporation) deposits decreased by €135.1 million, or 1.2%, over the month, and interest rates on new corporate deposits went down by 0.10 p. p.;
- loans to Lithuanian residents granted by credit institutions grew by €204.5 million, or 1.1%, while interest rates on new loans decreased by 0.08 p. p.;
- loans for consumption granted to Lithuanian residents grew by 2.1%, over the month, while interest rates on new loans for consumption went down by 0.26 p. p.;
- loans to Lithuanian corporations expanded by €407.5 million, or 2.7%, whereas interest rates on new loans grew by 0.21 p. p.;
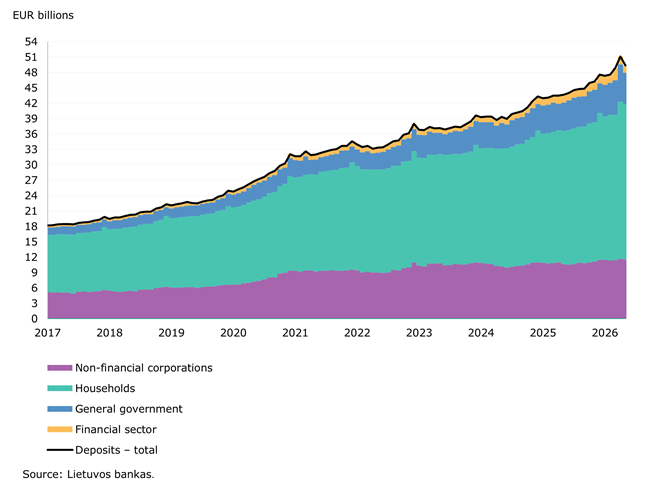
deposits of Lithuanian residents with credit institutions1 declined by €1,706.7 million, or 3.3%, over the month (their annual growth rate2 was 13.0%). Deposits of households and non-financial corporations decreased by €338.3 million and €135.1 million, or 1.1 and 1.2% respectively (their annual growth rates stood at 16.6% and 8.8% respectively). At the end of the month, household and non-financial corporation deposits amounted to €30.3 billion and €11.5 billion respectively. Deposits of the general government and financial sectors contracted by €1,133.4 million and €99.9 million respectively in May 2026. At the end of the month, these deposits amounted to €6.2 billion and €1.4 billion respectively (see Chart 1);
| Chart 1. Deposits of Lithuanian residents, excluding MFIs, with other MFIs (outstanding amounts, end-of-period) |
 |
overnight deposits of Lithuanian households and non-financial corporations with credit institutions decreased by €257.6 million and €169.2 million respectively, month on month, or 1.2% and 1.7%. At the end of the month, the outstanding amounts of overnight deposits of these sectors stood at €22.0 billion and €9.6 billion respectively. Household deposits with agreed maturity held with credit institutions declined by €87.0 million, or 1.1%, over the month, while those of non-financial corporations grew by €34.6 million, or 2.0%. At the end of May 2026, the outstanding amounts of these deposits stood at €7.9 billion and €1.8 billion respectively;
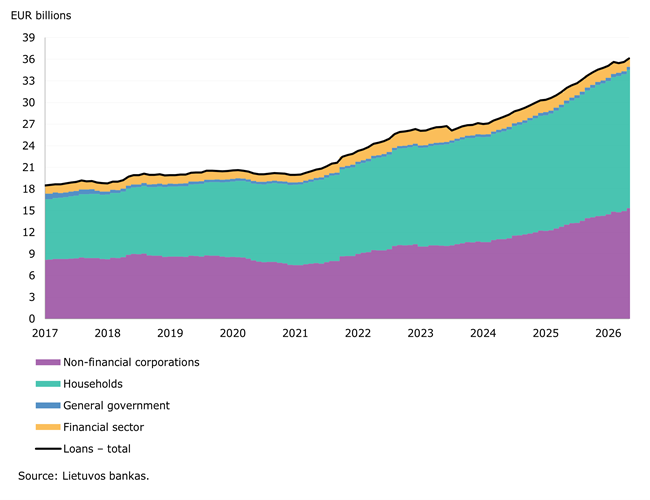
loans granted by credit institutions to Lithuanian residents increased by €494.6 million, or 1.4%, month on month (their annual growth rate was 12.9%). Loans to Lithuanian households and non-financial corporations increased by €204.5 million and €407.5 million respectively, or 1.1% and 2.7% (their annual growth rates stood at 14.2% and 17.6% respectively). Loans to the general government sector grew by €3.1 million, whereas those to the financial sector declined by €120.5 million. At the end of May 2026, loans to these sectors amounted to €19.2 billion, €15.3 billion, €436.1 million and €1.2 billion respectively (see Chart 2);
| Chart 2. Loans granted by other MFIs to Lithuanian residents, excluding MFIs (outstanding amounts, end-of-period) |
 |
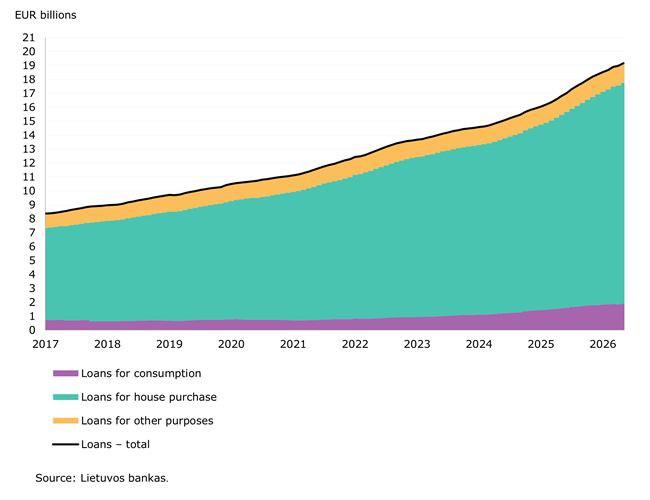
loans to Lithuanian households for house purchase, other purposes and consumption granted by credit institutions rose by €159.2 million, €6.0 million and €39.3 million or 1.0%, 0.4% and 2.1% respectively over the month. At the end of May 2026, the outstanding amounts of those loans stood at €15.9 billion, €1.4 billion and €1.9 billion respectively (see Chart 3), while annual growth rates stood at 14.1%, 5.2% and 23.3%;
| Chart 3. Loans granted by other MFIs to Lithuanian households (outstanding amounts, end-of-period) |
 |
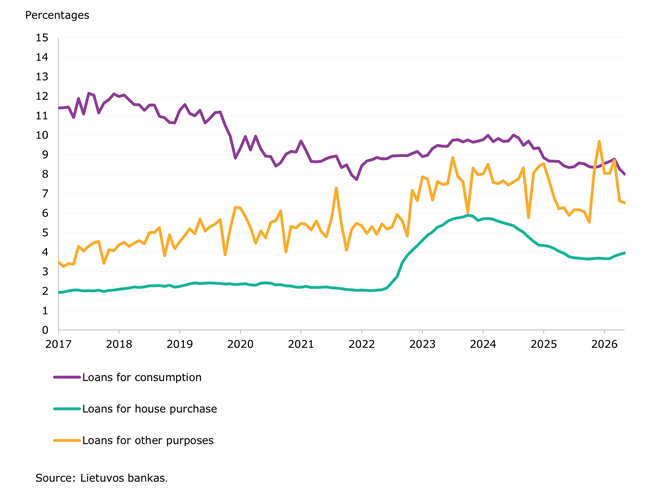
interest rates3 on new loans4 granted to households by credit institutions fell by 0.08 percentage points to 5.66%. Interest rates on loans for house purchase rose by 0.07 percentage points, while those on loans for consumption and other purposes fell by 0.26 and 0.10 percentage points respectively. In May 2026, interest rates on these loans comprised 3.96%, 8.00 and 6.53% respectively (see Chart 4);
| Chart 4. Interest rates on new loans for households |
 |
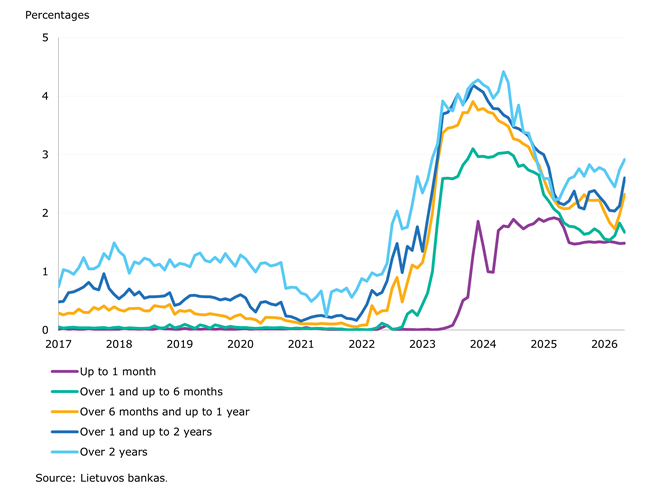
interest rates on new household deposits with agreed maturity held with credit institutions increased by 0.14 percentage points month on month to 1.93%. Interest rates on deposits with agreed maturity of up to 1 month, 6 months to 1 year, 1 to 2 years and from 2 years onwards went up by 0.01, 0.35, 0.48 and 0.18 percentage points respectively, while those on deposits with agreed maturity from 1 to 6 months went down by 0.16 percentage points. Interest rates on these deposits comprised 1.49%, 2.32%, 2.60%, 2.92% and 1.67% respectively in May 2026 (see Chart 5);
| Chart 5. Interest rates on new housing deposits with agreed maturity |
 |
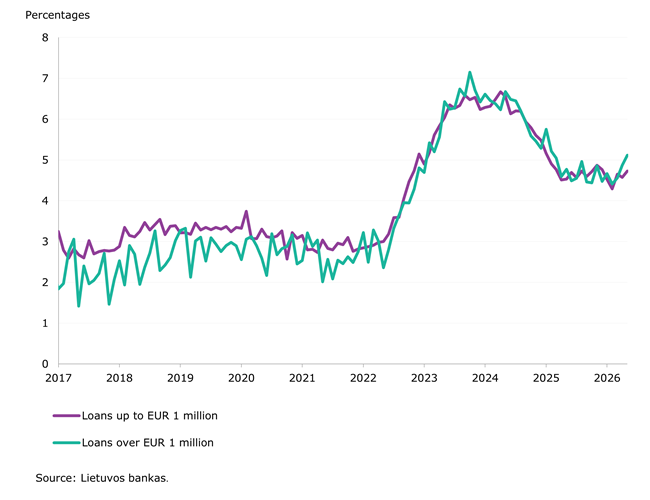
interest rates on new loans to non-financial corporations went up by 0.21 percentage points month on month to 5.02%. Interest rates on new loans of up to €1 million and over €1 million increased by 0.16 p. p. and 0.24 p. p. respectively. In May 2026, interest rates on those loans stood at 4.73% and 5.12% respectively (see Chart 6);
| Chart 6. Interest rates on new loans to non-financial corporations |
 |
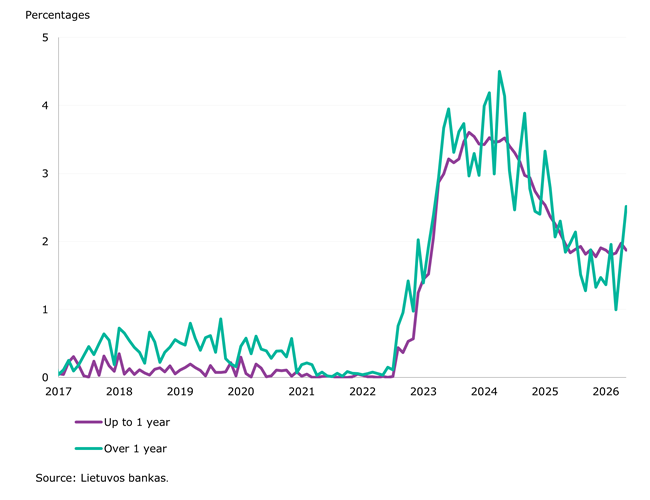
interest rates on new non-financial corporation deposits with agreed maturity declined by 0.10 percentage points month on month to 1.88%. Interest rates on deposits with agreed maturity of up to 1 year decreased by 0.10 p. p. and those with agreed maturity from 1 year increased by 0.74 p. p. In May 2026, interest rates on these deposits stood at 1.87% and 2.52% respectively (see Chart 7).
| Chart 7. Interest rates on new non-financial corporation deposits with agreed maturity |
 |
Detailed data on MFI assets and liabilities is available on Lietuvos bankas’ website under MFI balance sheet and monetary statistics.
Detailed data on MFI interest rates is available on Lietuvos bankas’ website under MFI interest rate statistics.
Use the My Datasets tool to create your own data sets, which are saved in your account and automatically updated as soon as they are published.
1 Unless otherwise specified, monthly changes in euro are presented as transactions, i.e. calculated by taking the difference between end-of-month outstanding amounts and removing the effects of revaluation adjustments, exchange rate adjustments, loan write-offs and reclassifications.
2 The annual growth rate is calculated as a percentage change in the base index of transaction-adjusted outstanding amounts over the year.
3 Interest rates on new loans and deposits are interest rates on new business. New business covers financial contracts that specify for the first time the interest rate on a loan or the deposit rate, and contracts for existing loans or deposits, which were renegotiated. New business does not cover revolving loans and overdrafts, as well as credit card debt. New business deposits do not cover automatic renegotiations of existing deposit contracts.
4 Weighted interest rates on new business during the reporting month, in percentages per annum.
Download in PDF (182.2 KB download icon)