
2026-03-26

Balance Sheet and Interest Rates of Monetary Financial Institutions, February 2026
Today, Lietuvos bankas published the balance sheet and interest rate data of the monetary financial institutions (MFI) for February 2026, which show that:
- Lithuanian resident (household) deposits increased by €395.4 million, or 1.4%, over the month, and interest rates on new deposits declined by 0.09 percentage points;
- corporate (non-financial corporation) deposits declined by €151. million, or 1.34%, whereas interest rates on new corporate deposits went down by 0.06 percentage points;
- loans to Lithuanian residents granted by credit institutions grew by €146.5 million, or 0.8%, while interest rates on new loans went up by 0.16 percentage points;
- loans for consumption granted to Lithuanian residents grew by 1.0% over the month, while interest rates on new loans for consumption went up by 0.10 percentage points;
- loans to Lithuanian corporations expanded by €359.4 million, or 2.5%, whereas interest rates on new loans fell by 0.26 percentage points;
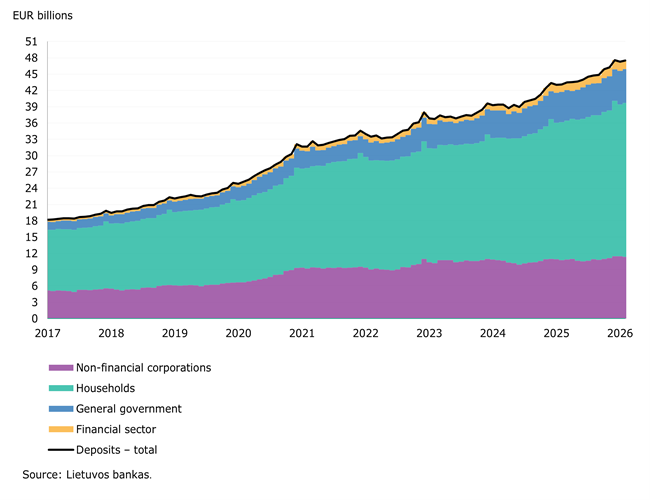
deposits of Lithuanian residents with credit institutions rose1 by €193.2 million, or 0.4%, over the month. (their annual growth rate2 was 10.4%). Household deposits increased by €395.4 million, or 1.4%, while non-financial corporation deposits went down by €151.0 million, or 1.3% (their annual growth rates stood at 11.7% and 5.8% respectively). At the end of the month, household and non-financial corporation deposits amounted to €28.3 billion and €11.4 billion respectively. In February 2026, general government deposits expanded by 50.9 million, while financial sector3 deposits fell by102.0 million. At the end of the month, these deposits amounted to €6.2 billion and €1.6 billion respectively (see Chart 1);
| Chart 1. Deposits of Lithuanian residents, excluding MFIs, with other MFIs (outstanding amounts, end-of-period) |
 |
overnight deposits of Lithuanian households held with credit institutions rose by €375.1 million, or 1.9%, month on month, while those of non-financial corporations declined by €100.2 million, or 1.0%. At the end of the month, the outstanding amounts of overnight deposits of these sectors stood at €20.1 billion and €9.5 billion respectively. Household deposits with agreed maturity held with credit institutions grew by €11.4 million, or 0.1%, while those of non-financial corporations declined by €51.8 million, or 2.9%. At the end of February 2026, the outstanding amounts of these deposits stood at €7.9 billion and €1.8 billion respectively;
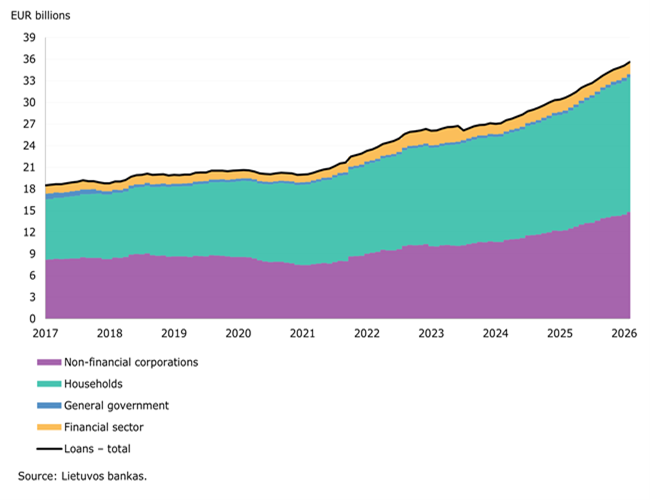
loans granted by credit institutions to Lithuanian residents increased by €508.8 million, or 1.5%, month on month (their annual growth rate was 16.2%). Loans to Lithuanian non-financial corporations and households went up by €359.4 million and €146.5 million, or 2.5% and 0.8%, respectively over the month (their annual growth rates stood at 20.5% and 15.4% respectively). Loans to general government grew by €5.2 million, whereas those to the financial sector declined by €2.3 million. At the end of February 2026, loans to these sectors amounted to €14.8 billion, €18.6 billion, €452.8 million and €1.7 billion respectively (see Chart 2);
| Chart 2. Loans granted by other MFIs to Lithuanian residents, excluding MFIs (outstanding amounts, end-of-period) |
 |
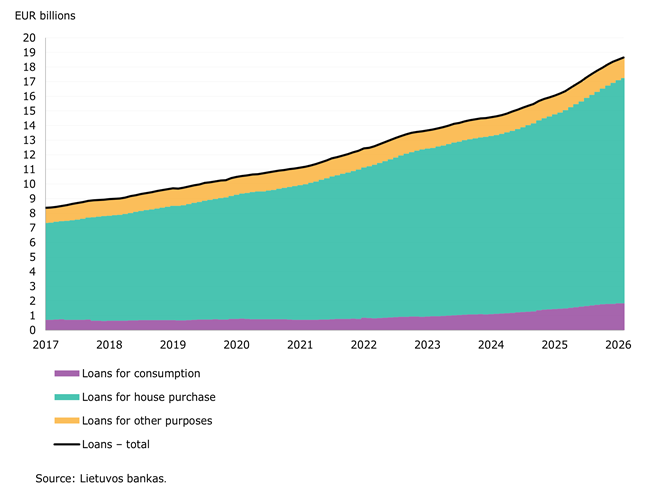
loans for house purchase and consumption granted by credit institutions to Lithuanian households grew by €134.8 million and €17.4.7 million, or 0.9% and 1.0% respectively, month on month, whereas loans for other purposes declined by €5.7 million, or 0.4%. At the end of February 2026, the outstanding amounts of those loans stood at €15.4 billion, €1.8 billion and €1.4 billion respectively (see Chart 3), while annual growth rates stood at 14.6%, 29.1% and 8.4%;
| Chart 3. Loans granted by other MFIs to Lithuanian households (outstanding amounts, end-of-period) |
 |
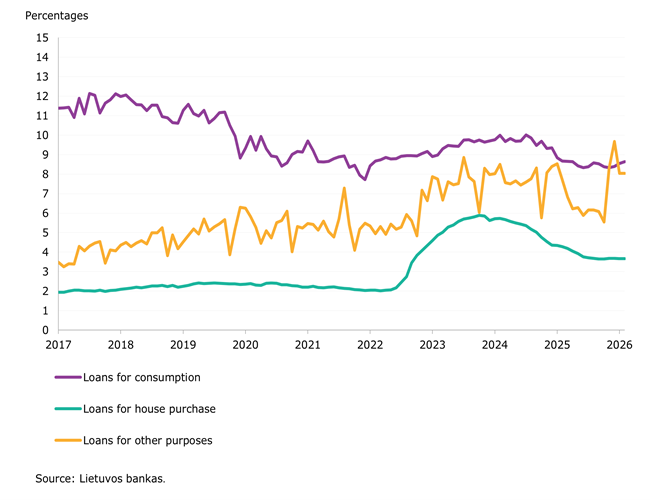
interest rates on new4 loans granted to households by credit institutions5 grew by 0.16 percentage points to 5.70%. Interest rates on loans for consumption and other purposes rose by 0.10 and 0.002 percentage points respectively, o while those on loans for house purchase decreased by 0.002 percentage points. In February 2026, interest rates on these loans comprised 8.65%, 8.04% and 3.67% respectively (see Chart 4);
| Chart 4. Interest rates on new loans for households |
 |
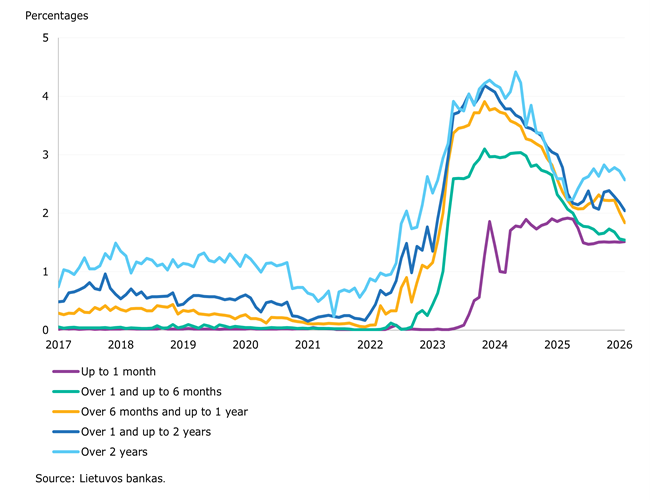
interest rates on new business of household deposits with agreed maturity held with credit institutions decreased by 0.09 percentage points month on month to 1.65%. Interest rates on deposits with agreed maturity of up to 1 month increased by 0.01 percentage points, while interest rates on deposits of 1 to 6 months, 6 months to 1 year, 1 to 2 years and from 2 years onwards went down by 0.02, 0.18, 0.13 and 0.15 percentage points respectively. Interest rates on these deposits comprised 1.51%, 1.54%, 1.84%, 2.04% and 2.57% respectively in February 2026 (see Chart 5);
| Chart 5. Interest rates on new housing deposits with agreed maturity |
 |
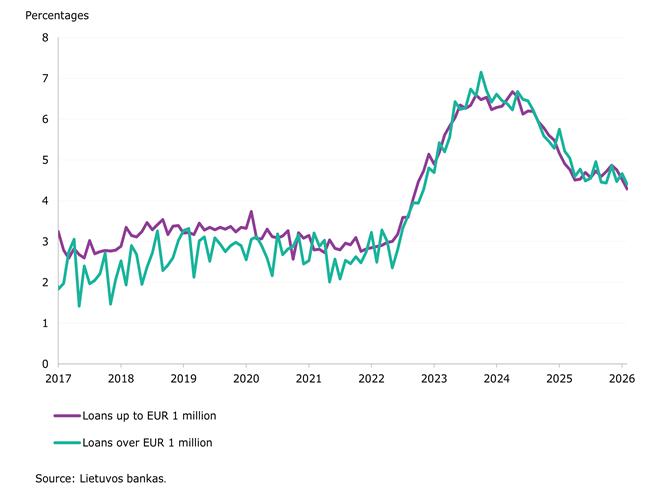
interest rates on new business of loans to non-financial corporations decreased by 0.26 percentage points month on month to 4.37%. Interest rates on new loans up to €1 million and over €1 million decreased by 0.24 and 0.26 percentage points respectively. In February 2026, interest rates on those loans stood at 4.29% and 4.41% respectively (see Chart 6);
| Chart 6. Interest rates on new loans to non-financial corporations |
 |
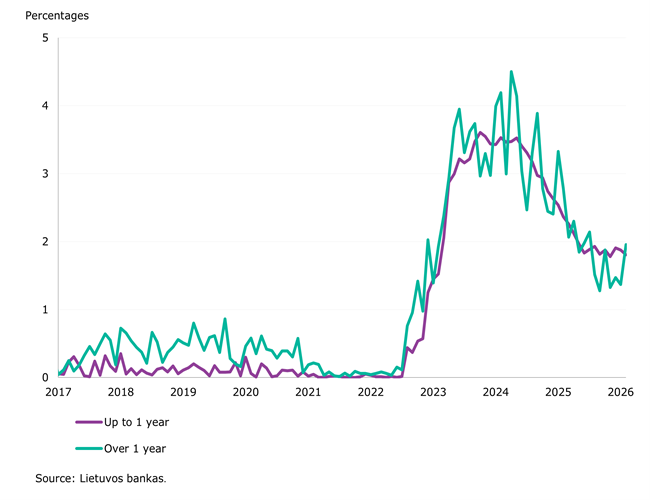
interest rates on new non-financial corporation deposits with agreed maturity decreased by 0.06 percentage points month on month to 1.81%. Interest rates on deposits with agreed maturity of up to 1 year and from 1 year onward decreased by 0.16 and 0.02 percentage points respectively. In February 2026, interest rates on these deposits comprised 1.81% and 1.96% respectively (see Chart 7).
| Chart 7. Interest rates on new non-financial corporation deposits with agreed maturity |
 |
Detailed data on MFI assets and liabilities is available on Lietuvos bankas’ website under MFI balance sheet and monetary statistics.
Detailed data on MFI interest rates is available on Lietuvos bankas’ website under MFI interest rate statistics.
Use the My Datasets tool to create your own data sets, which are saved in your account and automatically updated as soon as they are published.
1 Unless otherwise specified, monthly changes in euro are presented as transactions, i.e. calculated by taking the difference between end-of-month outstanding amounts and removing the effects of revaluation adjustments, exchange rate adjustments, loan write-offs and reclassifications.
2 The annual growth rate is calculated as a percentage change in the base index of transaction-adjusted outstanding amounts over the year.
3 The financial sector consists of Lithuania’s investment funds and other financial intermediaries, as well as insurance undertakings and pension funds.
4 Interest rates on new loans and deposits are interest rates on new business. New business covers financial contracts that specify for the first time the interest rate on a loan or the deposit rate, and contracts for existing loans or deposits, which were renegotiated. New business does not cover revolving loans and overdrafts, as well as credit card debt. New business deposits do not cover automatic renegotiations of existing deposit contracts.
5 Weighted interest rates on new business during the reporting month, in percentages per annum.
Download in PDF (173 KB download icon)